Should You Buy Now or Wait for Rates to Drop in Chattanooga? (2026 Guide)
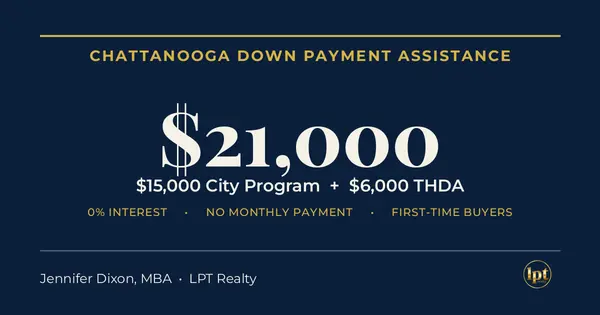
A week ago or so, I eie a post where I walked through the $21,000 sitting on the table for first-time buyers in Chattanooga. The question that comes right after that one, almost every time, is: okay, but should I even buy now — or just wait for rates to drop first?
Here's my answer, and it's not complicated: Marry the house, Date the rate.
What that actually means
The house is the part you can't get back. The right floor plan, the right lot, the right neighborhood, the one that actually fits your life — that's what you're really shopping for, and homes like that don't sit around waiting on a headline about the Fed. The rate, on the other hand, is temporary. You're not stuck with today's number forever. If it drops, you refinance. If it doesn't, you're still living in the house you actually wanted, not the one you settled for while you waited.
Waiting for a "better rate" to buy the house is dating the wrong thing.
The forecast that already got it wrong once this year
Before we get to the math, you need to see this, because it's the whole reason "just wait for rates to drop" is a riskier bet than it sounds.
Back in January, the big forecasters — Realtor.com, Redfin — were calling for 30-year rates to average 6.3% in 2026, a real step down from 2025. Rates actually cooperated for a minute: they fell through January and February, bottoming out at 6.01% on February 19th. If you were sitting on the sidelines then, waiting felt like it was working.
Then rates turned around and climbed. By late August they were back up to 6.71%. As of this week, they're at 6.83% — higher than they were seven months ago, not lower. Fannie Mae had to revise their own forecast mid-year because of it: back in September of last year, they were projecting 5.9% by the end of this year. By May, they'd already walked that back to "near 6.3% through much of 2026" because reality was running hotter than their model. And here we are in September, sitting almost half a point above even that revised number.
So when you hear "rates are expected to hit 5.9% by December," you're hearing a forecast from an institution that's already missed twice this cycle — once in February, once again by May. That doesn't mean it can't happen. It means I'm not going to tell you to structure your life around it happening.
The math, if it does happen
Here's the refinance case, with the caveat above fully attached. On a $350,000 loan, the difference between today's 6.83% and Fannie Mae's (already-revised-once) 5.9% target is about $213 a month in principal and interest. If rates actually get there, you buy now, refinance later, and pocket the difference every month after that — without having spent the back half of this year on the sidelines.
If they don't get there — which, per the last seven months, is a real possibility — you're still in the house you actually wanted, at a rate you can afford today. That's the whole point of not betting the purchase itself on a forecast with a losing streak.
A local option built for exactly this situation
If "date the rate" is the plan, it helps that some lenders have actually built a product around it. Jennifer Toomey, a senior loan officer with CMG Home Loans here in Chattanooga, walked me through theirs: it's called Rate Rebound, and it's built for exactly this scenario. Once rates drop at least 0.5% from what you locked in, you can refinance and CMG waives their own lender fees — processing, underwriting, tax service, appraisal, and credit report — and adds up to $1,000 toward third-party costs on top of that.
It's not a full cost wipeout — discount points aren't covered, and there's a 6-month wait after your original closing before you can use it — but it takes a real bite out of the "refinancing isn't free" problem. If you buy now and rates ease the way forecasters keep predicting (with the track record from above in mind), this is one concrete way to make that plan cost you less than doing it on your own. Worth a conversation with her directly if the numbers on a specific house have you weighing this: Jennifer Toomey, CMG Home Loans.
Prices haven't been waiting either
Here's the part that usually gets left out of the "just wait" argument: home prices in Chattanooga haven't paused for anyone while rates bounce around. In June 2024, the median sold price here was $327,586. As of this July, Redfin has it at $368,815 — up 5.4% in the last year alone, and up roughly 12.6% over that two-year stretch.
I'll be straight with you: not every data source agrees on the exact number. Zillow's smoothed home-value index actually shows Chattanooga essentially flat to slightly down over the past year, which measures something a little different than the median price of what actually sold. Different methodologies, different answers — that's real, and I'm not going to pretend the data is cleaner than it is.
But here's what all of it agrees on: there's no reliable signal anywhere that says "prices are about to drop significantly, so wait for that instead." At best, prices are holding roughly flat; at worst — the more supported case — they've kept climbing right through the same stretch rates did. Waiting doesn't get you a materially cheaper house. It just risks a still-uncertain rate on top of a price that, if anything, has been trending up.
Or you let the equity do the work instead
Refinancing isn't the only payoff, and given the last section, maybe not even the most likely one. The other path: you buy now, and whatever the market does with prices from here, you're the one holding the equity instead of the one trying to buy into it later. If Chattanooga keeps doing what it's done the last two years, that 12.6%-type move is the spread you capture by being in the house already, instead of still shopping for it.
Either path works — lower payment if rates actually cooperate, more equity to move up on if prices keep doing what they've been doing. You don't get to pick which one happens. But you don't get either one if you were never in the house to begin with.
What waiting actually costs you
Nobody talks about the cost of waiting because it doesn't show up on a rate sheet. But it's real: the house you wanted goes under contract to someone else. Rent (or your current mortgage) keeps getting paid either way, building someone else's equity instead of yours. And if rates do eventually ease, you're not the only one who notices — buyer demand comes back all at once, and you're competing for the same house with more people and less leverage than you'd have today.
Buying now doesn't mean overpaying or settling. It means locking in the house while you have real negotiating room, and treating the rate as the thing you fix later, not the thing you wait on now.
The honest caveat
Forecasts are forecasts, not guarantees — and this cycle's forecasts have already been revised once, mid-year, in the wrong direction. Refinancing still has real costs even with a program like Rate Rebound — discount points aren't covered, third-party credit caps at $1,000, and you're waiting at least 6 months either way — so it's a real bite taken out of the cost, not a free do-over. Price data isn't perfectly clean either — different sources, different numbers, and I'd rather show you that mess than smooth it over. And none of this is financial advice; it's the same logic I'd walk any buyer through, but the right call for your specific numbers is a conversation, not a blog post.
The takeaway
You can't control the 10-year Treasury. You can control which house you end up living in. Buy the one that's actually right for you now, and let the rate be the thing that improves later — because it's the only part of this equation that's actually designed to change.
Wondering what today's rate actually does to your numbers on a specific house? Let's run it together. Book a call with me.
Jennifer Dixon, MBA, LPT Realty
Categories
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "