Chattanooga Down Payment Assistance Program: How to Get Up to $21,000 (2026 Guide)
 Every first-time buyer I've talked to in the last few weeks has asked me some version of the same question: "Wait, is that down payment program real?"
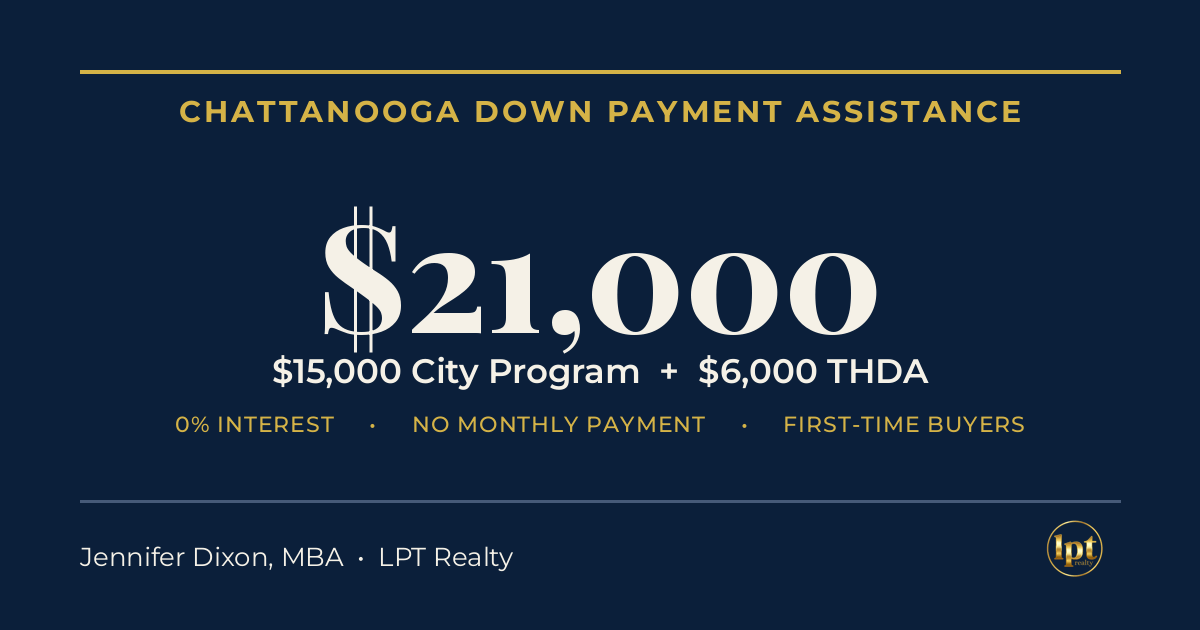
It is. The city rolled out $21,000 in down payment assistance for first-time buyers this year, and it's gotten covered by every local news outlet in town. What none of that coverage tells you is how it actually works, who actually qualifies, and what it actually takes to use it. So let's do that part.
What the money actually is
This isn't a grant you keep no matter what, and it isn't a second mortgage payment stacked on top of your first. It's a 0% interest, deferred loan — meaning no monthly payment, ever. You only pay it back when you sell the house or do a cash-out refinance. Until then, it just sits there quietly doing its job.
The breakdown:
- Up to $15,000 from the city's own program
- Stack it with Tennessee's THDA program and it goes up to $21,000 total
That's real money toward a down payment, not a rebate or a rate discount dressed up to sound bigger than it is.
Who actually qualifies
Here's where "free money" coverage always gets vague, so let's be specific:
- First-time buyer means you haven't owned a home in the past 3 years — not "never in your life."
- Household income can't exceed 120% of the area median income. For 2026, that's roughly $81,800 for a single person up to $135,600 for a household of six — it scales with family size, so don't rule yourself out based on a number that doesn't match your situation.
- The home has to be inside Chattanooga city limits and priced at $400,000 or less. This is the one that trips people up — a lot of the areas I show buyers (Hixson, for example) sit outside the city line and won't qualify. Ask before you fall in love with a house.
- You need $1,000 of your own money in the deal. This isn't a zero-out-of-pocket program.
- A homebuyer education course is required before closing — it's a real class, not a checkbox, and your certificate is good for 12 months.
- You have to work with a participating lender. Not every lender in town is signed up for this, so this is step one, not step three.
What it actually looks like, in order
- Find a lender who's actually approved for this program — don't assume yours is.
- Complete the homebuyer education course.
- Get pre-approved.
- Find a property that fits: in city limits, $400K or under.
- Get it inspected — this is mandatory, not optional, before closing.
- Go through underwriting like any other loan.
- Close — the assistance gets applied directly by the closing agent, you're not handling a check.
None of that is complicated. It's just a specific order, and skipping the lender step first is the most common way people waste weeks.
The honest caveat
This program is genuinely good, and I'd rather you know exactly what it is than assume it covers more than it does. It won't help you buy in Hixson, East Brainerd, or across the county line in Georgia — it's Chattanooga city limits only. And $400K is a real ceiling in some of the areas people ask about most. If your search is centered outside the city, this isn't your program — but there may be others that are, and that's worth a real conversation, not a guess.
The takeaway
$21,000 toward a down payment is not a small thing, and for a lot of first-time buyers, it's the difference between "someday" and "this year." But it only works if you do the steps in the right order, starting with the lender question, not the house-hunting one.
If you're wondering whether you qualify — or whether the house you're already eyeing is even in the zone — let's just talk it through. Book a call with me.
Jennifer Dixon, MBA, LPT Realty
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "